Personalized Mortgage Guidance. Powered by Supreme Lending.
Personalized Mortgage Guidance. Powered by Supreme Lending.
Meet the team
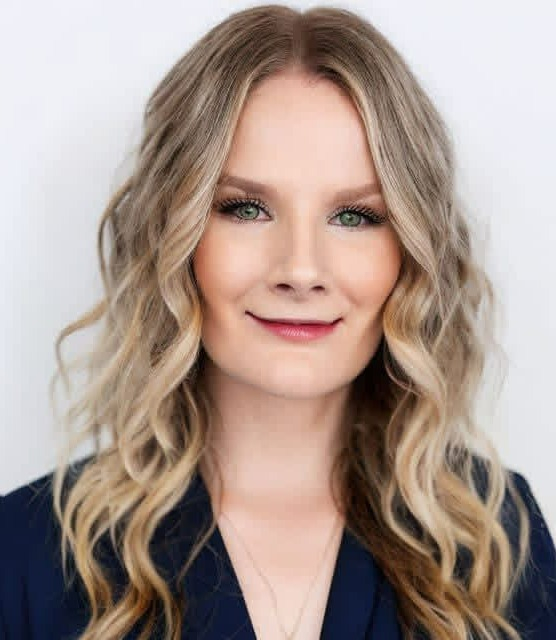
Martha Erdek
Branch Manager
NMLS #1484131
3215 Henderson Drive
Jacksonville, NC 28546
Branch: 214.340.5225
Cell: 908-763-6383
Eddie Soriano
Mortgage Loan Officer
NMLS #2536752
Veteran/USMC Retired
3215 Henderson Drive
Jacksonville, NC 28546
Katie Breedlove
Mortgage Loan Closer
As our Loan Closer, Katie oversees the crucial final stage of your transaction. Once your loan receives clear-to-close approval, she prepares all final legal disclosures—including your Closing Disclosure (CD)—and coordinates directly with closing attorneys and settlement agents. Katie ensures funds are disbursed on time and that signing day goes smoothly, so you can focus on celebrating your new home.
Paige Brill
Mortgage Loan Processor
As our Loan Processor, Paige is the anchor of the approval process. Once your loan application is underway, she works behind the scenes to gather and organize your financial documentation, coordinate with title companies and appraisers, and resolve any outstanding underwriting conditions. Paige keeps communication open and clear, ensuring your file is 100% complete and ready for final approval.
Zach Griep
Loan Officer Assistant (LOA)
As Loan Officer Assistant to Martha Erdek, Zach plays an essential role in driving your home financing journey forward from day one. He serves as the primary liaison between borrowers, loan officers, and processing teams—managing early document intake, pre-approval details, and client communication. Zach’s hands-on support and proactive follow-through ensure that every file moves seamlessly into processing while delivering a clear, stress-free experience for our clients and real estate partners.
Loan Programs
Explore our program offerings, a variety of financing solutions to fit every situation.
conventional loans
Conventional loans are a cornerstone of home financing. They offer flexibility, competitive interest rates, and options for both first-time and experienced homebuyers.
Key Features
– Down payments as low as 3% for first-time buyers
– Competitive fixed and adjustable rates
– No upfront government insurance fees
– Option to remove PMI once you reach 20% equity
Eligibility & Guidelines
– Credit score typically 620 or higher
– Debt-to-income ratio up to 45%
– Available for primary residences, second homes, or investment properties
Ideal For
– Borrowers with good credit and stable income
– Homebuyers looking for flexibility and low long-term costs
– Homeowners refinancing for better terms
fha loans
FHA loans make it easier for more borrowers to achieve homeownership. Backed by the Federal Housing Administration, these loans feature low down payments and flexible credit requirements.
Key Features
– Down payments as low as 3.5%
– Credit scores as low as 580 may qualify
– Competitive fixed rates
– Assumable loans for easier resale
Eligibility & Guidelines
– Must occupy the home as a primary residence
– FHA-approved appraisal and property standards required
– Upfront and monthly mortgage insurance apply
Ideal For
– First-time homebuyers
– Borrowers with limited credit history or smaller savings
– Families looking for affordable entry into homeownership
USDA LOANS
USDA loans offer zero-down financing for homes in eligible rural and suburban areas, helping families enjoy affordable homeownership outside major city limits.
Key Features
– 100% financing (no down payment)
– Competitive fixed interest rates
– Low mortgage insurance costs
– Flexible credit requirements
Eligibility & Guidelines
– Property must be in a USDA-eligible area
– Income limits apply based on household size
– Primary residence only
Ideal For
– Buyers seeking affordable homeownership in rural or suburban areas
– First-time buyers who meet income and location criteria
JUMBO LOANS
When your dream home requires financing beyond conforming loan limits, Jumbo Loans provide the solution. Ww offer tailored jumbo financing to help you move forward with confidence.
Key Features
– Loan amounts exceeding conforming limits
– Competitive interest rates
– Flexible terms and structures
– Options for primary residences, vacation homes, and investment properties
Eligibility & Guidelines
– Strong credit and income required
– Larger down payment often needed (typically 10–20%)
– Appraisal and reserve requirements apply
Ideal For
– Buyers purchasing high-value homes
– Borrowers with complex financial portfolios
VA LOANS
VA loans are designed for veterans, active-duty service members, and eligible surviving spouses. With zero down payment and no monthly mortgage insurance, they’re one of the best paths to homeownership for those who’ve served our country.
Key Features
– 0% down payment
– No private mortgage insurance (PMI)
– Competitive interest rates
– Flexible credit and debt guidelines
Eligibility & Guidelines
– Must have a valid Certificate of Eligibility (COE)
– Must occupy the home as a primary residence
Ideal For
– Veterans and active-duty service members
– Eligible surviving spouses
– Buyers seeking affordable, no-down-payment options
RENOVATION LOANS
Turn a fixer-upper into your dream home with renovation financing that combines your purchase and improvement costs into one simple loan.
Key Features
– One loan, one closing
– Low down payment options
– Finance cosmetic or structural renovations
– Available for FHA (203k) or Conventional (HomeStyle) borrowers
Eligibility & Guidelines
– Minimum credit score typically 620+
– Licensed contractors required for all work
– Home must be primary residence for FHA; flexible for Conventional
Ideal For
– Buyers purchasing homes needing updates
– Current homeowners refinancing to renovate
FAQs
Why should you get Pre-Qualified?
Getting pre-qualified for a mortgage is a great first step to kickstart your homebuying journey. Pre-qualification gives you a picture of how much you may afford based on your credit, income, and debt. It helps you determine your budget, understand estimated monthly payments, find the right loan program, strengthen your offer, and save time.
Which loan program is the best fit?
What are closing costs?
applying for a loan, you’ll receive a Loan Estimate outlining these settlement charges for added fees like loan origination, appraisal, credit report, title insurance, document preparation, prepaid interest, and other miscellaneous fees.
The taxes will be the same on either type of loan. A common mistake is that people believe is their taxes will vary depending on the loan they choose. The title company that closes the loan submits the taxes directly to the lender. If you reside in an attorney state, your representation is the one who orders the tax certificate from the appraisal district. Taxes reported to the lender will be included in your monthly loan payment. There is no mark-up or service charge over and above the actual tax amount.
Homeowner’s insurance works the same as taxes. You pay the lender for your policy amount on a monthly basis. The lender will escrow this amount and send it to your insurance company at the end of the year when renewal is due.
Interest rate differences will vary depending on the lender you choose. Most importantly, ALWAYS ask for the lowest rate for the type of loan you are obtaining.
The principal and interest portion of the payment is calculated by configuring the loan amount (MIP rolled into the balance on FHA) and term into an amortization schedule to calculate the payment amount. Ask your Prospera Home Loans Powered by Supreme Lending representative for additional information on conventional and FHA loans.
What Home Price Fits My Budget?
What goes into a monthly mortgage payment?
A monthly mortgage payment includes several components often referred to as PITI: principal, interest, taxes, and insurance. Any condo fees or homeowners association fees may also be factored into a monthly payment.
What documentation may be needed?
• Income history and employment verification from the past two years, such as tax returns, W-2s, and 1099s (if applicable)
• Asset statements for bank, retirement, and brokerage accounts
• Monthly debt payments, including any outstanding loans and credit cards
• Records of rent payments, divorce, bankruptcy, or foreclosure
Mortgage Calculator
Enter a few details below to estimate a home price that may fit within your budget.
Ready to Get Started?
Whether you’re a first-time homebuyer, upgrading, or refinancing,
our team is here to guide you every step of the way.